Scaling AI in Banking: Why Core Systems Matter More Than Ever
As banks accelerate GenAI and Agentic AI initiatives, core systems have become a strategic enabler of success. Watch this American Banker webinar featuring Amdocs and Celent experts as they explore how modernization unlocks trusted data, operational
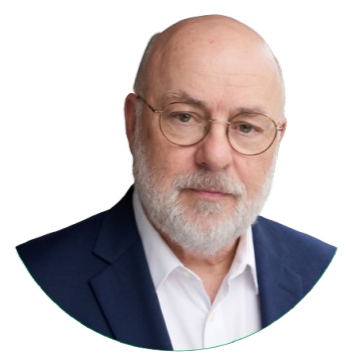
Paul Holland - Chief Technology Officer, Amdocs Mainframe Practice
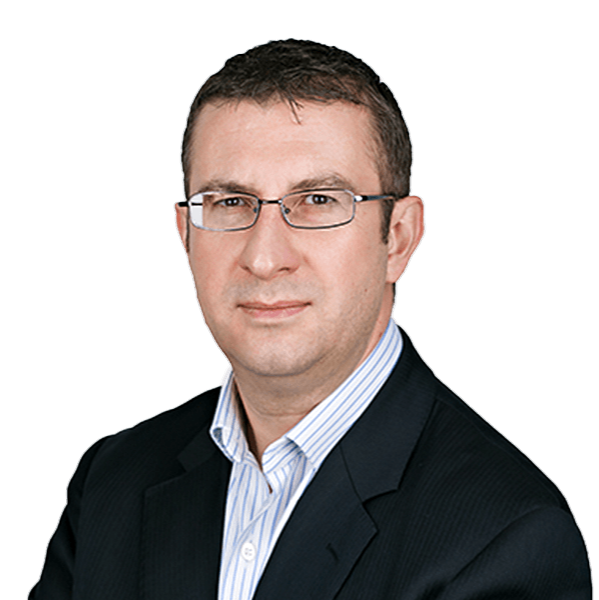
John Researcher - Principal Analyst, Retail Banking Celent
09 Oct 2026
Please provide your details
Asterisk (*) indicates required field.
Thank you!
Your submission has been forwarded to the appropriate contact.
Banks are moving quickly from AI experimentation to enterprise-scale deployment. Yet many of the data assets, transactions, and business processes that power AI remain embedded within core systems. Watch this webinar to learn why modernization is becoming a critical foundation for AI success in banking.
The banking industry's AI ambitions are accelerating. Financial institutions are investing in GenAI and Agentic AI to improve customer experience, strengthen risk management, streamline operations, and increase software delivery productivity. However, many banks are discovering that scaling AI requires more than advanced models. It requires access to trusted data, integration with core business processes, and a technology foundation capable of supporting enterprise-wide intelligence.
In this American Banker webinar, experts from Amdocs and Celent discuss why modernization has become a strategic priority for financial institutions seeking to unlock the full value of AI. Drawing on industry research and real-world observations, they examine how resilience, customer experience, cybersecurity, cloud adoption, and AI initiatives are increasingly converging around the modernization of core banking environments.
The discussion explores practical approaches for modernizing mainframe and legacy environments without disrupting mission-critical banking operations. Topics include workload placement across hybrid environments, API-led integration, modernization pathways for core applications, and strategies for exposing business logic, processes, and data to support future AI-driven use cases.
"The future of banking AI depends on trusted data, resilient operations, and seamless integration across core systems."
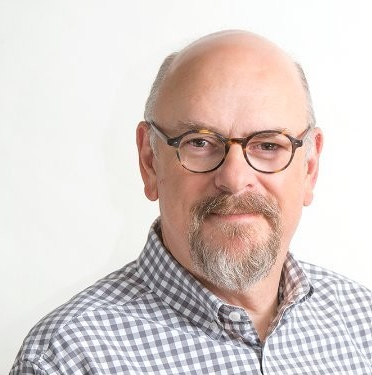
Paul Holland
Chief Technology Officer, Amdocs Mainframe Practice
The webinar also examines the rise of Agentic AI and its growing role in modernization programs. Rather than replacing human oversight, banking leaders are increasingly looking to AI agents to assist with application analysis, testing, validation, orchestration, and modernization planning while maintaining governance, deterministic engineering controls, and regulatory compliance.
Viewers will gain insights into how leading financial institutions are balancing innovation with operational resilience, why complete mainframe exits remain uncommon, and what steps banks can take today to create an agent-ready architecture that supports both modernization and long-term AI transformation.
Greetings. I'd like to welcome everyone in our audience today. We are very grateful that you have chosen to share some of your busy day with us. We know your time is valuable, and we'll honor that today with what I am confident will be an engaging discussion. Once again, our topic today is scaling AI in banking, why core systems matter more than ever. Our sponsor today is Amdocs Studios. Our host is American Banker, and my name is Mike Sisk. I'm contributing editor at American Banker, and I will be your moderator today. And I am very pleased to introduce our two speakers today. We have with us Paul Holland, chief technology officer at Amdocs' studios, and also Daniel Mayo, principal analyst retail banking at Sellent. And, actually, I'd love to have, each gentleman, introduce themselves a bit. Paul, please, let's, start with you. Thanks, Mike. Hello, everyone. It's a great pleasure to be here with you today. As Mike said, I'm the CTO for mainframe modernization at Amdocs. I've had, gosh, about over forty years, in the application modernization space, which actually spans a wide variety of platforms. But probably about the last twenty years, I've been very much focused on, mainframe applications and and looking at how legacy, applications and data can be modernized to meet the needs of the business. Over to you, Dan. Thanks, Paul. So I'm a principal analyst at. For those of you who don't know, is a financial services specific analyst house. I'm on the banking team with a primary focus on banking platforms. So I've been tracking the core banking market with... Not quite for forty years, but certainly coming up to thirty years. I'm based in London, but spent many years over in The US market. And I guess to Kiera, as I look at our modernization strategies for core banking, broader enterprise architecture, cloud migration, and as with many people more recently looking very much at the impact of artificial intelligence. So great... As with Paul, great to be with you here today. Excellent. Excellent. Thank you both. Alright. So just before we jump into things here, I wanted to reiterate two quick notes that were in that housekeeping video that that played a little while ago. And that is we do have time for q and a. We have a little time set aside at the at the very end, but you don't have to wait until the end to put your question in the queue. Definitely put that question in as it occurs to you throughout the hour, and we will make every effort to get to it in the time we've got. If we run out of time, we'll definitely follow-up with your question after the program. So please ask away. We very much wanna hear from you. We also have a couple polls today, and I always encourage a 100% participation. I rarely get it, to be honest, but I do encourage it. We we do share the results live here, and it's a great way for everyone to see where everyone else stands on the issue we've come together to discuss. So if you can weigh in on that... On those polls, that'd be fantastic. And so let me just kind of sort of set the stage here a little bit, kind of share with, you the, the agenda here, what we're going to explore today. We're gonna start off with, how banking priorities are converging, then, the core transformation choices. We'll move into agentic AI changes, the delivery model, and then the foundation for an agent ready bank. And then as I said, after that, we'll we'll we'll do... We... We'll also have some q and a as well. So... And I think what I'm gonna do now is roll in actually to that very first poll. And what I'm gonna do here is I'm just gonna read the question, read the couple answers that are... That you... Options that you have for answers, and, hopefully, that'll give you enough time to make a selection. So which issue is putting the greatest pressure on your bank's technology agenda today? Is it security and operational resilience, legacy and core modernization, AI adoption, customer experience and digital channels, cost reduction and operational efficiency, or would you say regulatory compliance? So I'm gonna hold it open a little bit longer here just to... I've got a little handy tool that lets me see how many folks are participating. It's nice to... I like to try to hold it open and make sure we get a nice percentage of our viewership here today and get a real feel for what the audience is thinking. So... Alright. Actually, really great participation. Thanks, everyone. Really appreciate it. Okay. Good. I think I will go ahead and share the results. Yeah. Great. Thank you, everyone. Alright. So here are the results. So we got legacy and core modernization led the way here at 24%, followed by AI adoption 20%, security and operational resilience 18, customer experience and digital channel 16, cost reduction and operational efficiency also 16, and just 6% mentioned regulatory compliance. So thank you very much for those results. And, Dan, let me just pivot over to you and ask you, are you surprised by any of these results, kind of are these in line with what you were thinking? So from my perspective, actually broadly in alignments, we've actually got some data I'll show you in a minute with a similar question. So it's always quite comforting to see that we were broadly aligned with it at the start of the webinar. Yeah. I I see how the other one's been. I I would just jump in and and say, I think this shows our audience is in the right webinar. So that's always reassuring as well. Right? Sorry, Dan. Over to you. So, Dan, you can take it away. Cool. That's fine. So thanks a lot, Mike. So, yeah, as I said, I've got a a similar chart and similar question to start with. So to provide some context, I kind of wanted to start at the top and and look what's kind of really driving IT strategy and that's investment priorities for kind of North American banks at the moment. So this chart here shows you data taken from seventh Dimensions survey program. So this is an annual study of finance institutions from across the world. But what I have here is North American data focused on acceptives from the retail banking side. So if you think about IT strategy, it's obviously driven by a whole range of factors. But when acceptors are asked to prioritize the top drivers, it is kind of interesting to see what are the most pervasive for the sector and also understand how this changes over time. So starting from our study that was conducted kind of early on this year, there were two clear drivers, and you can see that on the chart here. So the first one I point out was enhancing customer experience, which got relatively high on our initial survey there. And certainly for us, the North American market is a very competitive one for retail banking. Customer satisfaction and the quality of interaction is a critical factor for for banking, particularly on the digital side, but I would also say for the branch and contact center. And I would say, actually, The US market is slightly, to some degree, unique in this because, actually, if you look at most other regions, certainly Asia Pacific, Europe, Latin America, where you tend to find these banks have a stronger focus on kind of product and proposition innovation over a customer experience. And that often reflects the kind of local markets where many markets outside The US, you have a kind of high bank concentration with a few large banks rather than the highly competitive market you have in The US. The other driver you can see here is around operational resilience and IT security, And this has really risen up the agenda over the last decade partly because of the security challenges around digital banking, which has become kind of more prevalent as the primary channel for for most banks, but also resilience itself really has been on the registry forefront. And in contrast, the customer experience, this is quite a global thing. So we've had DORA in Europe. We've had recently 21 guidelines in Canada, sound practices, kind of guidelines from the Fed. And this does look at the use of kind of critical third parties and does impact modern platforms as well. So regulators, for example, have been looking at cloud concentration risk, but it has also forced banks to evaluate long term sustainability and the operational risks around legacy platforms. And just from an analyst perspective, the last five years, we've really seen an acceleration of banks asking us around kind of evaluation of mainframe strategies, something that I would say over the last thirty years has probably been more talked about on a periodic case, but never has really gained much momentum. And tied into that is the third driver you can see here, which has actually seen quite a notable shift moving into 2026, which is around legacy modernization. And you can see here it's often cited as a second or particularly third choice as a top driver, but has become quite notable in North America, which I would say is a market that has been relatively quiet around this issue, especially compared to, many other regions in recent years. I think it's also worth, seeing how these drivers vary between kind of Canada and The US and by kind of tier segment within The US. So we've grouped together the kind of tier one and two banks into... Large banks here and two, three, and and four banks as a medium here. And interestingly, you can see that this focus on operational resilience is really dominant in The US, whereas in Canada, kind of banks seem to be more focused on kind of wider compliance and regulatory requirements here. I would say this is partly a reflection of the different kind of regulatory timescale kind of movements here. I mean, e twenty one in Canada has just come into effect, so we saw a lot of the spending impacts in 2024 and in 2025. In The US, I would say the regulators have been prioritizing, and they kind of really started with the large banks here. You can still see for The US large, it's still important here, but you can also see it has become of quite clear importance for small banks now. And I'll say particularly those within that kind of 1 to 20,000,000,000 assets at the top end of the small bank segment there is important. The other clear difference that you can see here is around legacy modernization focus, and this has really been particularly driven by the tier one to four US banks. Partly, would say, sort of probably see more pervasive use of generation one kind of your four legacy kind of platforms here, greater use of mainframe systems. Conversely, smaller banks tend to make great use of kind of some of the vendor packages out there. In many cases, the vendor is often kind of managing the maintenance burden of the platform, kind of hosting or running themselves, And this often hides some of the complexities behind it, though not always the cast. And interesting here, you can see kind of banks have a stronger focus on the product proposition our innovation with these area... These banks tend to often to be stronger on the kind of customer experience side, but weaker in terms of product breadth and depth. And I would say, conversely, this kind of reverse is is true for the large and medium banks there. So talked a bit about that kind of regulatory push on operational resilience, which in turn has been driving a renewed appetite for legacy modernization. But the other factor, I think, has been important here, and I guess this is slightly more of the kind of carrot rather than the stick regulation, has been the impact of artificial intelligence. So we first started to see this really from around 2024 when the kind of first wave, particularly around kind of generative AI took off. But you can see for the chart looking at technology investment priorities for 2026 that artificial intelligence along with cybersecurity are by far the kind of most pervasive technology focus areas for the sector. And, traditionally, you would typically see a kind of more balanced perspectives across the range of technologies for the sector, but you can really see artificial kind of dominating at the moment. I would say this interest comes from a number of areas. First, from the board level, I guess the potential of AI to really define the banking business model has very quickly reset the executive ginger so you have this kind of chop down kind of prioritization there. Secondly, banks have started to see and harvest the benefits from AI, particularly in some areas like IT development and the ability to accelerate development life cycles. I've certainly seen this on the digital platform side of things. And thirdly, what we have seen is the focus of AI has shifted kind of from generative AI, particularly in '24 and '25, to kind of our focus now on agentic AI. And while, really, for most banks, agent... Use of agentic AI is still in early stages, often used to support kind of AI assisted or kind of AI powered kind of workflows rather than true end to end or agentic AI. I I think the potential of agentic AI to really change banking is coming to the fore here. So the key question we're getting from our banking clients is really kind of how do you incorporate kind of modern AI technology stacks into legacy architectures? So in particular, do you move on to a new system first to be able to really leverage and fully utilize the kind of advantages of AI? Or do you look to kind of modernize, incorporate AI kind of sooner but potentially with more constrained capabilities? What are the key questions that we're seeing in the market now? So looking at the barriers to innovation more generally, but for many, this is going to be particularly focused on AI. Banks do face a number of constraints here. And while kind of use of AI, particularly around development, is starting to produce some benefits, for most banks, there's still this fundamental issue around capacity. And you can see for most banks here, kind of much of the development, the change the bank budget is effectively kind of pre allocated to meeting and supporting kind of mandatory requirements. And for most banks, cost management is very much still a real issue. So one of the things we do is track kind of budget growth for 90 spending with banks. Typical kind of rates for most banks in the in The US has been around kind of four to 5% per year kind of over the last decade. And now what we're seeing now is that needs to support kind of increasing infrastructure hardware costs, ironically, a result of the kind of wave of investment in AI. And most banks still have a shortage of develop capacity even with the kind of increasing use of the kind of these AI tools to improve productivity there. The other factor, though, is limitations with the kind of existing technologies. And for many banks, this is particularly true of kind of the kind of core banking and the payment systems with kind of use of older platforms, older languages. And that often means banks can't adopt kind of agile approaches to development. There's often limited windows to kind of to be able to make changes, and testing requirements are often kind of both costly and lengthy here. I think one of the interesting shifts we've seen with this question here is we've seen many banks actually move towards more agile approaches, particularly over the last five years or so, kind of agile at scale, creation of tribes, etcetera, particularly for kind of the digital platforms. And this has kind of driven a a kind of improvement in kind of cooperation between the business and technology functions and that business IT alignment, which used to be a major issue. But for most banks, the capacity issue is still very much there. So looking to where banks are prioritizing investment for 2026, we can see from this chart kind of three top priorities. So digital channels, financial crime, and risk. Probably worth explaining... Expanding this chart a little bit here because I I realize it's a little bit complex. So we asked, know, our dimension program kind of two questions here. So the the first one is kind of where across the different business functions are your top investment kind of spend areas for 2026. That's shown on the x axis here. So for most banks, kind of digital banking, kind of financial crime, fraud were the kind of key areas here. But then we also asked for each kind of funk... Business function area kind of what were their investment growth plans for the coming kind of eighteen months here. And what we show is the kind of net growth score here based on the proportion planning to increase spending. So you can see for fraud and financial crime, the vast majority of banks are looking to increase the spend here. And then the size of the bubble kind of combines both to kind of show you relative investment prioritization score. So I guess the interesting thing having talked about legacy modernization before is that account administration, which is where the bulk of sending the kind of core banking platforms would be, is a relatively low investment priority for banks as a whole. It is significant probably for about a fifth of banks, but it's an area which banks are generally trying to constrain spend. So often investment requires efficiency gains to kind of fund further investment. In contrast, if you look at kind of digital channels, they are the top investment area for the vast majority of banks, and most institutions are still increasing spend here even though this has been quite a strong focus area really for the last kind of ten to fifteen years. Interesting, though, when you kind of ask questions as to where institutions are looking to planning to use AI, there's more of a balance across the different business functions. So this chart is based on a series of questions that we asked where they were looking to invest in AI, getting them to consider what they're doing around generative AI, agentic AI, and kind of more traditional kind of machine learnings. So you can see here that digital channels are still important as is financial crime, which are kind of key investment areas kind of overall. But there's also a strong focus on using AI to support other channels. So this is particularly the contact center here, product development, and operations. And, certainly, if you look at Agentic AI, operations for the... By financial crime is the top area for this area here, particularly as banks are looking to get efficiency savings. I would say here the change, though, is while banks aren't necessarily looking to incorporate Agentic as much into account administration or payments, for agents to be effective within operations and financial crime or the kind of channels, they need to be able to interact in kind of real time and access information processes and know how within the kind of core banking and payments functions. And in fact, a lot of the kind of domain knowledge and requirements specific to banking is embedded in these systems. So you might have a a kind of generic model that you're using to support it, but you need to be able to act... Interact and work with these systems really for these agents to be kind of banking agents rather than generic kind of AI agents. So last bubble chart here. So one of the things we're seeing now as a result of this is while banks aren't necessarily looking to spend significantly on account management functions, what we are seeing is that core banking is one of the top areas here that banks are looking to transform. So you can see this on the x axis here where we kind of say, are you looking to kind of do either kind of maintain or do kind of transformation or replace systems within there. Actually, kind of core banking was the second top area after kind of fraud and financial crime. I would say for most... Many banks, this has shifted to being a kind of long term goal that we're doing in the next five years or so to a medium term one. So kind of over the next two to three years, which is why it's slightly lower down on the y axis, which is the kind of the time frame question we ask compared to maybe, like, fraud or digital channels here. And, obviously, it's also an area that we're seeing banks, even though it's a mission critical one, that banks are increasingly open to use of new approaches such as software as a service, though I would say, overall, that is stronger in the areas that are seeing kind of lots of new investment where banks are looking to get new platforms, particularly in areas like the fraud of financial crime and digital channels. Gonna skip my screens coming back up. Here we are. So I guess the question is why is this? And for us, the secondary question is kind of why now? Haven't covered this for for many, many years. The why now, I think, is particularly important here. And I'd say while many kind of mainframe based legacy platforms have been kind of, to many of these, faithful workhorses, and to be fair, many of them do the job they were designed for very well, The nature of what a bank is and what it needs to do is changing an AI world. So agents need to be able to interact with data processes and capabilities within the core applications in real time. And while to some degree you can use it to intake AI to overcome some of these issues with legacy platforms, it doesn't provide the foundation for for agentic processes and agentic commerce in the longer term. And then alongside this, banks need to ensure long term operational resilience while supporting the next wave of scalability. So banks over the last kind of fifteen, twenty years have already seen exponential volume increases driven by kind of digital banking and then particularly mobile banking, and that's gonna accelerate further with agentic kind of commerce. So for banks to kind of... What we're seeing is the kind of the factors of cost, the ability to change, the ability to innovate is driving a focus now. So as we saw on the previous slide, I wouldn't say every bank is looking to do this in the immediate term. But what what we're seeing as more banks do start to modernize this platform, this is starting to create competitive pressure on others to kind of use... New technologies. So just the last slide for me before I kind of hand back over to Mike and Paul is actually while we are seeing some banks actually looking to replace cores with new platforms, the majority of banks kinda looking to transform over or looking to actually kinda transform and modernize their existing ones. So doing things like refactoring, rearchitecting, improving the ability to work alongside kinda new platforms and incorporate AI, kind of adding API layers, adding MCP layers, for example. And this is particularly true if we're kind of meeting to large banks in The US, kind of the the the kind of light blue bars there. With the smaller banks that already work with friends of platforms, there is kind of more openness to kind of switching and transforming. And interestingly, the Canadian banks are also kind of more open to replacements. So, I would say this is more with the small to medium bank segment here, which certainly have a kind of smaller market share compared to The US market. So that's what we're seeing in the in the market at the moment. What I'd like to do now is hand over to Mike to get a perspective of our audience around this question here. Mike, over to you. Excellent. Excellent. Thank you, Dan. Alright, everyone. Here comes our second poll. And same drills before, I'm just gonna read through the the the question, a couple of answers here, and everyone please just take that time to to weigh in. So which approach best reflects your bank's core modernization strategy for the next five years? Is it to optimize and modernize primarily on the mainframe, move selected workloads while retaining the core, transform the core platform incrementally, replace the core with a new platform, pursue a full mainframe exit, or is your strat... Your strategy... Is your strategy still being defined? So, once again, I'll just hold that open for another couple of moments, but, seeing a lot of great participation again. Really appreciate that. Makes the results all the more meaningful when we get a nice percentage of our audience here. Yeah. Great. Yep. Just about exactly the same as the first poll. Very much appreciated. Alright. Let me go ahead and share the results here now. K. Alright. 32% said strategy is still being defined. That's the... That was the vote... Top vote getter, followed by, 30% said move selected workloads while retaining the core. And then after that, transform the core platform incrementally 17%, optimizing and modernizing primarily the main from 11, replacing the core with a new platform 6%, and only 4% said pursuing a full mainframe exit. So thank you very much for those results. And, Paul, let me kick it over to you now. What are what are your thoughts on these results? Are these of in line with what you might have expected? Yeah. They... I I think they are, Mike. Yeah. I'm I'm I'm not surprised at all, the majority being we still need to work out what the plan is, what the the strategy is. And that's actually happen than you think given the changes in in the, in the whole area of legacy transformation at the moment. But the rest really fall in line, and, that 4% at the bottom there, I know a man in our organization who would love to talk to you about that mainframe exit strategy. So reach out, please. It... That's a good segue, I think, into into this because, Dan touched on a a a really good point early in his presentation, which is the relevance of transformation modernization of the core. It's in... Particularly in US banks. It's been talked about for a long time, but, you know, how much real action has been taken over the years. And what was shown on this chart is what we have seen as the the, somewhat incremental strategies, which, you know, was referenced in in the poll there, that the banks are are taking around the core. And the first thing I think is, you know, is this realization. Maybe it isn't about a full mainframe exit, but there is perhaps an opportunity and even a need to look at hybrid platform compute and, aligning workload placement to the right platform. So a lot of work was done early on around digital channels and pushing digital channels out into distributed and even even possibly cloud in in some cases. I think as you peel back from that to business function applications and then maybe, maybe starting to look at the core, there is now, I think, willingness to say, you know, just because it was first built on the mainframe, it doesn't have to be on the mainframe. And, we are seeing, a lot of our banking customers looking more, flexibility and and optimization because, obviously, there's opportunities for cost, improvement and that kind of thing by looking at where these workloads should be placed in a hybrid compute, world. And almost as a byproduct of that because now not everything is stacked up on one, one platform, you've gotta have a means of integrating everything together. But also to foster agility and the ability to be flexible in these layers that you're building out, we've seen this this drive to really create an API driven architecture even as that touches old legacy environments as well. I'm looking at at enabling technology for creating API or even event driven processing all the way through into the legacy is something that we are seeing as a sort of initial step of modernization. And then I think incremental was talked about in the poll and this idea of strangling the core. You know, a lot of peripheral processing was built around the core on the mainframe because then it was easy to do, and that's what you had. But now I think as things can be moved away, then this idea of chipping away, not necessarily hitting the core over the last few years, but looking at the stuff around that, the peripheral modules that may exist around that and how those can be pushed out away from the mainframe and into more modern, architectures. And then I think, you know, whether it is actually a mechanism for transformation, but but also a driver for transformation is the whole area of AI adoption and how that how that is now, as Dan touched on, starting to look at, you know, what does that mean from a transformation of the core point of view. The reality is that if you take those actions, it's, I think, fair to say that most, banks, large, medium scale banks, are actively engaged in modernization processes that either are now immediately touching the core directly or, as we've mentioned, you know, handling those peripheral capabilities around the core while still preserving the core. And there is, in in many cases, quite large scale endeavors, to to drive those those transformational projects. But I I guess the the question is, and I think the feeling that we're seeing in the market... And by the way, the... These these figures you're seeing here have taken the very recent, hot offer, a survey we just wrapped up, which was global, but focused on certain industry verticals, and banking was, one of the key ones. And I think the question is, what results are these, current activities yielding? And I think what we're seeing is, a fairly slow pace of transformation. And the nearer you get to the core, the slower that pace becomes. So there clearly is an issue of how we're enabling and and speeding up, modernization as we get closer and closer to the core. K. Refresh that. There you go. And and I think there is a a theme in banking, and the poll absolutely reflected this in only 4% of the respondents saying that they were looking to shut the mainframe down. I think in banking, there is a general realization that the mainframe still can be a fit for purpose platform. It has, you know, it has its its own cost structures and and those things that are somewhat, misaligned with the rest of the, of the industry. But nonetheless, it's a valuable platform and can serve a valuable function for the banks. So the idea, I think, of keeping the mainframe in place, somewhat modernizing in place, on the mainframe is still probably, very attractive to most banks and and also most feasible to most banks because, you know, a more radical, exit from the mainframe may be very difficult to achieve and quite impactful. But then it raises the issue of how do you modernize and replace and how do you how do you still, gain the benefit of a modernization transformation when you're still somewhat restricted on the technology sets, survival technology sets that are gonna run, in a mainframe environment. And that's something where I feel, some of the things that are being done around agentic AI, which we're gonna talk about in a minute, could be could be very impactful. So I think, again, the conclusion that we're seeing out of the survey that we, we just conducted is that transformation is occurring. It is occurring, around the core and in the core. And the most banks see it as a prerequisite to achieve their, cloud and, importantly, their AI, goals, because, obviously, one of the challenges that everybody's facing with the implementation of AI and agentic AI, for actual business processes is realizing the productivity gains that have been promised. Right? And we actually have have been put a great bit of investment into, Agentic AI. Are you gonna get the productivity payback? And the reality is that productivity improvement is only going to, be achieved if the surrounding environments that those agents are working within, and applications that they're working with are in a form that that enables them to be deployed efficiently and effectively. So I think increasingly, we're gonna see the, implementation and need to implement Agentic AI as also a driver, to modernize. And therefore, for that reason, again, this survey, August, 26, 88% of, of the banks that we spoke to are increasing their funding around modernization. So, I think you put that in the balance of what Dan's, showed, because this is, in many respects, this is seen as business as usual in, spend in banks, core banking, systems, are not necessarily the focus of innovation and not necessarily gonna drive that level of investment. But if you look at the level of investment against the sort of business and usual investment that those, applications were attracted, then there's definitely money being spent on an increase in in that. And then the interesting thing, which I think is very important because while we're looking at how transformation and modernization can enable, agentic AI implementation from a business perspective, one of the key things that is gonna impact transformation of legacy environments and is impacting transformation legacy environments today is the use of agentic AI. And the respondents that we asked about this really saw AI as becoming essential for large scale modernization within the next two to three years. And that's something that that we're seeing a lot and and we agree on. And and, actually, I think Dan raised the point that one... You know, if you if you look at at the introduction of agentic AI beyond business processes and you actually look at the use of that within IT itself as, an aid to, software development life cycles and then improvement in productivity there, then using agentic AI to drive modernization and transformation legacy actually also enables and sets up very nicely the idea of using agentic AI for ongoing software development and maintenance and the full, development life cycle. So, there's a... We... We're seeing this with certain customers at the moment now. There's almost a a desire for customers to get their hands dirty with using agentic AI for modernization because that yields those capabilities into future, developments as well. So, with that said, I'm gonna hand it back to Mike to, ask this question of you all, and we'll do another poll and keep getting this feedback because it's it's really useful. It's very encouraging to see. So over to you, Mike. Excellent. Excellent. Thank you, Paul. Yes, everyone. So here's our our third poll, and I will... Let let us proceed as we have for the first two. So where would your organization be comfortable using AI agents in modernization today? Analyze and document applications and code, recommend modernization approaches and plans, generate tests and validate results, orchestrate modernization workflows, transform or rearchitect production applications, or are you not ready to use agents at this point? So, again, I'll hold this open. And just a reminder about our q and a at the end of our program here. So don't don't forget, you know, if you've got something on your mind, please go ahead and get those questions into the queue. And I don't know. We usually have about about ten minutes or so, Five or ten minutes to handle some questions. Alright. Good. Nice level of participation again here. Don't wanna eat too much into our remaining time, but... Yeah. Good. Let me just go ahead and share the results here now. Wonderful. Alright. So orchestrate modernization workflows, 24%. That led the way. These are... Is... This is pretty even across, actually. 21% said analyze and document applications and code. 19, recommend modernization approaches and plans. 17, generate tests and validation results. 17 said we are not ready to use agents, and only 2% said transformer rearchitect production applications. So interesting. Thank you again for that. And over to you, Paul, to reflect on these results real quickly. Yeah. This is great. In fact, I'm gonna jump to the next slide because this is what we find out. And it's, it's it's somewhat in line, although I think some of the some of the the the percentages that came off the poll in there were even more, acute, more drastic. But... And I find this fascinating because if you if you, you know, pay attention, and, of course, there was that very famous incident, a few months back where Amdocs made claims about, modernizing cobalt with Claude, and that had ripples throughout the industry. Right? So a lot of the noise in AI, for transformation at the moment is actually around code transformation. And yet our our survey showed that that was the area least, compelling at the moment. Right? Just less than 30% of of our audience said that they would look to use agents to transform applications. I think on the on the poll... Well, I don't know if I can go back. Can I go back, Mike, on the poll? I'm gonna try. Ah, there you go. On the poll, it was a staggering 2% of you would trust an agent to do your co conversion or at least, you know, rearchitect production applications, which I'm kind of loosely calling the co conversion. But we ask... And that... So I find that fascinating, and we'll look at we'll look at that a bit more on the following slide. But where I think we're... We are seeing in our survey absolutely reinforced what, what the polling said there. Using agents to analyze and document existing applications, I think it's pretty well proven pathway now. Right? Using AI to do that, and there's a great deal of benefit in doing that, particularly around the extraction of, business functionality and and business capabilities embedded in applications. That's very useful. And, yes, definitely, and the poll showed this as well. There's great potential, and, you know, we're already exploiting this as well, in in using, agents and AI to accelerate and automate and, in fact, even debug and remediate testing around, transformation work. The the other thing we added to our poll was the use of deterministic. And by deterministic, I mean more of a sort of rules based, pre outcome, sort of functional equivalent transformation, capability, which, of course, is the sort of automation that companies have been, like ours, have been using for for many years now. And I think there's still a role for that. There's still a role, a, for deterministic transformation, kind of classic refactoring for maybe less strategic applications. And, and there's a, I think, a role there that was supported by our survey findings to actually utilize that capability to make agentic AI better. So we have a point of view on that. And if anyone would like to understand that more, please reach out to me, and I'll I'll explain that more to you. But at the same time, as this hesitancy around maybe where a, agentic AI and AI in general, generative AI is gonna help with the process of transformation, There is a great consensus that within probably the next three years, application modernization and transformation will be a largely agentic AI driven process. And, honestly, I think, you know, that will be also re architecting applications. And, you know, we're doing work in that space, and, frankly, we've seen some pretty encouraging results on that. I think it's just getting... It's getting people to a point where they're comfortable with that, and and that's achievable. But I think the market understands you as people in this industry understand that it is going that way. And and that's why that very beginning strategy question of, you know, where are you on your modernization? And many were still trying to work out strategy. I think a lot of that has to do with the fact that the enabling technologies and the use of agentic AI to drive these transformation projects is still, building and and, you know, may may have more influence to come. Okay. This, I think, is our last poll. So we don't know where you at, but, I'll I'll pass it back to Mike because he does a great job. He sees the results coming in. So over to you, Mike. Thank you very much, Paul. Yes. This is our fourth poll due, fourth and final poll, and do appreciate everyone's, participation here. So what is the biggest obstacle preventing your modernization program from moving faster? Is it a budget and competing priorities, limited skills or delivery capacity, complexity and undocumented dependencies, risk of operational disruption, unclear ownership or governance, or difficulty proving the business case. So very good. Again, responses are rolling in. Very much appreciated. We've got we've got just a couple more couple more slides from Paul after this, and then we will have some time for q and a. So definitely get those questions in there. Okay. Good. Don't want to. We only have about ten minutes left here, actually. Amazing. Time is flying this this hour. Okay. Let me go ahead and share these results. Okay. Budget and competing priorities that this top vote getter, third of you said that by risk of operational disruption, 26%, and complexity and undocumented dependencies, 21%. Those those three together made up the lion's share here. Another 12% said limited skills or delivery capacity. Paul, over to you. Yeah. That's great. That's great. Okay. Well, I'm gonna I'm gonna crack on with a little bit of pace, Max. I do wanna give us time to, answer your questions. I think one of the things we saw in our survey is, not that it's an inhibitor, but that it's, it's perhaps where there has been a pain or a a concern about, transformation modernization projects. And that is the amount of effort that it takes from, the core, IT, groups. And that's understandable because, you know, it's kind of additive. It isn't necessarily, functions that are, you know, driving business enhancements, although those can be baked in. So there is an overhead to this, and I think that's why, you know, we feel automation is always a key to this, and we feel, Agentic AI is gonna is gonna help compensate or overcome some of that resourcing, issue. But I liked that third one because the the the first one, you know, getting budget, well, that's always an issue. Right? Getting money is always an issue. So that's just... To me, that's background noise. Right? That's always gonna be the case. But that third one about, hey. What we've got is very complex. We know it's a great big bowl of spaghetti. There's a hell of a lot of interdependencies in there. Where do we start? How do we get our arms around the problem? That's it. That's where you start. Right? You start by understanding that. And I think that is that is something that doesn't have to take a large chunk of budget to achieve, by the use of tooling and automation and AI. I think that can be a very good way of of getting things moving. And, and with... And frankly, you can't start without doing that. Right? There is no point in trying to look at a single point of of a application. So let's go modernize that without understanding the implications of the whole. Alright. So just to bring that back to, where we started with this, which is, you know, how how does modernizing the core help accelerate and enable, the introduction of agentic AI for the business? And there's quite a lot of ways. But the the the sort of obvious ones, I think you probably already recognize, is a lot of that data around the core is not in a form that is easily accessible to any agentic workflows that you build. And so transformation of the data as a minimum is an important enabler. But as we go through, the the transformation, process, and particularly that first process of investigating and documenting, we can start to look at that business functions, those business functions, that business logic, and expose that to enable the creation of agents to, build out those business functions. And lastly, through transformation, we can make that core processing available to support agents, architecturally in the form of microservices or or whatever else. Okay. So that sort of wraps up the slides. We're gonna move to questions right now. I I have a couple of questions I wanted to ask Dan, but I'm not gonna do that because this is all about you guys. So so let's go straight to what we've got from the audience, Mike. Very good. Thank you, Paul. And I've got a couple good questions here, and let's just jump right in. So a question for Dan here. Were credit unions included in the sampling? So for those particular questions, they weren't. The focus would just be community banking, not credit unions. Okay. Very good. And and on our survey, Mike, we did not do credit unions either, but more more... You know, our bad, which we should probably should have done, but it was major retail banks was where we were focused. And here is a question. What is the difference between a major transformation and a full replacement in the context of our discussion today? So that's leave that in just because it's kind of the question I have for Dan as well, which my interpretation of that, Dan, is what is the difference between transforming the core or replacing the core with a a modern generation fintech? Yeah. So I think that the... What we're seeing here is full replacement would be moving on to a new vendor package either be a kind of modern traditional provider or some of The US ones or some of the next generation ones like a thought machine or or 10x there. We've generally only seen that for a fairly small proportion of banks. And and I think one of the the key challenges you see is actually unless you're looking to do a replacement as part of a far broader business transformation, is actually to get the benefits of of a new package. You need to be able to try and standardize the business processes and the business side as well as the technology because, actually, what you don't wanna do is end up massively customizing the kind of vanilla package that you're you're looking to kind of leverage and kind of get scale from there, which is why actually a lot of banks are looking to kind of mobilize because actually then you can leverage a lot of the, I guess, the heritage and the expertise that actually has been baked into existing systems, but look to kind of modernize the technology stack kind of to get... To allow us to use the new technologies. Excellent. Excellent. Thank you, Dan. Alright. Another question here. Probably both both of you guys would like to weigh on it. So rather than spending heavily on legacy patching and a p a... API wrapping, isn't a parallel modern stack with a phased cutover a faster path to AI readiness? How should banks weigh dual run costs against the AI bottleneck of running on legacy cores? Or shall I shall I say this one first, Paul? So actually, we... Yeah. We have seen a number of banks try to do this with the kind of side call approach, particularly with some of the next generation platforms. So, actually, the idea being you effectively run a a kind of modern bank in parallel. Most banks have just done this by starting with new product area or potentially move into new market or new customer segments. We have actually started seeing a couple of banks then use that and migrate the old platform onto that. So I would say that is still relatively few banks have actually done that successfully. And part of the problem is you still need to standardize and shift the kind of working processes from the old bank onto the new bank. So it it certainly improves the processes and and the ability to have a new platform, make sure it actually works and is is running. It doesn't often necessarily negate the pain points in terms of the transformation and the migration itself. Though, as with modernization, this may be an area that the agentic AI can also improve, provide kind of productivity benefits as well. Yeah. And the only the only thing I would add to that... I mean, I think it's a it's a it's a viable strategy. But I think as Dan indicated, when you actually weigh up cost, time, complexity, and risk, you, you know, you... It isn't it isn't necessarily going to be that much cheaper, that much faster, that less complex than than perhaps transforming what you have. And and while I haven't actually done a lot in banks, it is a very common pattern in the insurance industry, building in a new platform, putting new products on the new platform, maintaining old policies on the old platform. And what's very interesting about that is most insurers end up not migrating the old products and just focus on the new products on new platforms. So whether that would apply to banking, I'm not too sure. And, you know... But you could end up... If you're not careful and not committed, you could end up with the worst case, right, where you still have the old. But The whole just... The hardest thing we've seen is that you've been able to turn the mainframe off. And in many cases, they run-in the new system, but, actually, it's very difficult to actually fully decommission the mainframe unless you're very committed to it. Yeah. Interesting, though. Good question. That was a good question. Yeah. Fascinating. Fascinating. I I think we're gonna have to leave it at that. However, we're right at the top of the hour. Always wanna be respectful knowing that so many folks are shifting to the next their next obligation at the top of the hour. So first of all, let me thank Paul and Daniel both. Really appreciate your time and expertise here today digging into this digging into this issue and sharing all all that great research. And, of course, everyone in the audience couldn't be happier with with all of the questions you asked, all of the poll participation we had today. Really appreciate that. And would also ask that you keep an eye out for an email that'll be coming your way. It'll have a a link to a recording of this event and some other materials, that will be coming your way. And with that, I will officially wrap it up. Wish everyone a wonderful rest of the day, and I hope you'll join us again here very soon. Thanks so much.
Scaling AI in banking: Why core systems matter more than ever
Modernize the Core. Scale AI with Confidence.
Discover how banks are modernizing core systems, unlocking trusted data, and building the foundation needed for enterprise-scale GenAI and Agentic AI initiatives.
Related Insights
Paul Holland - Chief Technology Officer, Amdocs Mainframe Practice
John Researcher - Principal Analyst, Retail Banking Celent
09 Oct 2026
Guy Hilton VP of Strategy and GTM
Amdocs
24 Apr 2026
Guy Hilton, VP of Strategy and GTM
Amdocs
24 Apr 2026
Pablo Cella, President – Amdocs Studios Business
08 Dec 2025